Hyderabad Real Estate: Housing demand looks structurally supported by active office leasing market — Certus Research | Certus Capital
Certus Research
Hyderabad Real Estate: Housing demand looks structurally supported by active office leasing market
Certus Capital
·5 Minutes
Summary:
Hyderabad has established as a major hotspot of Indian real estate market with robust economy, superior infrastructure and a steady inflow of skilled talent.
Between CY16-1QCY26, Hyderabad recorded a cumulative net absorption of 74.1 msf, making it the 2nd largest office market among the top seven cities in India and globally, after Bengaluru.
While housing sales have normalised from the CY23 peak, Hyderabad’s share of pan-India sales value increased from 8.9% in CY21 to 12.0% in 1HCY26, reflecting its growing prominence and sustained homebuyer demand.
Combination of growing infrastructure, diverse businesses and an active office leasing market should further translate to employment opportunities and act as a primary catalyst for long-term residential consumption. With strong office market acting as an engine for housing sales, housing demand looks structurally supported.
City at a glance:
Hyderabad is one of the leading metropolitan economies in India, driven by expanding infrastructure, a deep talent base and a diverse business ecosystem (IT, Life sciences/Pharma, aerospace, financial services and defence).
Hyderabad city contributes ~ 54% of the Gross State Domestic Product (GSDP) of Telangana
Telangana contributes to 11% in India’s IT exports. Hyderabad is the 2nd largest contributor to revenues from IT exports of the country
~2k life sciences companies employing 5 lakh+ professionals
~ 515 global capability centres (GCCs) accounting for 20% of the India’s GCC base.
Presence of major educational institutions like ISB, IIT Hyderabad, IIIT Hyderabad, NIT Warangal, BITS Pilani Hyderabad, University of Hyderabad, Osmania
Ranked #1 most liveable city of India (WeAreCity 2026)
This economic strength has created opportunities across business expansion, investment and urban development leading to broad based real estate demand - office, housing and retail.
Hyderabad Residential Market:
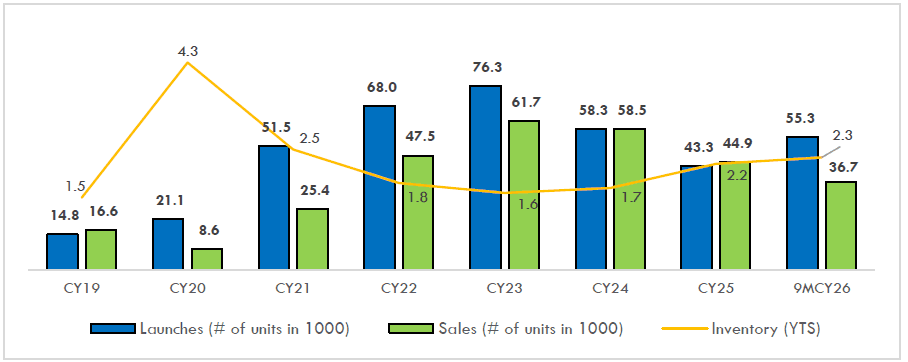
Backed by rising residential sales (sales increased from over 25k in CY21 to ~62k in CY23), residential launches increased from over 51k units in CY21 to a peak of more than 76k units in CY23. However, since 2024, the market has entered a more sustainable phase, with developers calibrating new supply to demand.
While housing sales outpaced launches in both CY24 and CY25, 1HCY26 launches have again outpaced supply resulting in inventory buildup.
Despite normalisation of housing sales, overall residential sales value grew by 3.6x from CY21 (INR 17k+ Cr) to CY25 (~INR 62k Cr).
Premiumisation has become a defining trend in Hyderabad housing market, with units priced more than INR 4.0 Cr and above accounting for ~10% of all new residential launches in 1HCY26, up from 1% in CY21.
Continued launch momentum (especially launches in the higher ticket size segment) over the last 3-4 years has resulted in increase of inventory overhang to 27 months (against a pan-India average of 19). Recalibrated launches by developers designed for mid-market options will be important to preserve affordability and support the workforce that strengthens the city’s office market.
Residential Market Performance
Source: Anarock Indian Residential RE reports
Hyderabad Office Market:
Hyderabad has established itself as one of the leading office markets in India and is the 4th largest office market in India in terms of completed office stock accounting for ~16% of India’s total stock as of 31-March-26.
Sustained occupier demand, a thriving technology ecosystem, continued expansion of GCCs, a deep talent pool, complemented by ongoing infrastructure development and a business-friendly environment, continue to reinforce the position of the city as a preferred destination for occupiers and institutional investors.
Office sector has performed well over the past two years with balanced supply pipeline and sustained leasing momentum.
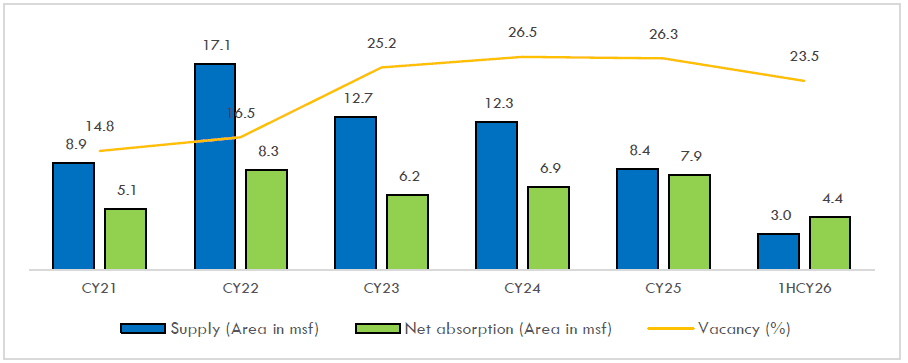
New office completions have moderated from a peak of 17.1 msf in CY22 to 8.4 msf in CY25 and now to 3.0 msf in 1HCY262.
Vacancy levels have declined from a high of 26.5% in CY24 to 23.5% in 1HCY262 with vacancy levels in HITEC City corridor at ~7%5 and 35%+5 in extended IT corridor (Financial District/Nanakramguda). Rentals in HITEC City market has increased to ~INR 90 psf pm1 on account of its preferred location with quality developments, presence of strong social & physical infrastructure coupled with well pre-committed near-term pipeline.
IT–ITeS and BFSI continue to drive office demand in Hyderabad with expanding GCC operations further strengthening leasing momentum.
GCCs have expanded their footprint from 1.9 msf in CY21 to 4.5 msf in CY25 and more than 3 msf in first half of CY26. Their sustained contribution to total office leasing reflects the city’s growing prominence as a preferred destination for multinational occupiers.
Office Market Performance
Source: Anarock Hyderabad RE report H1 2026
Investment Thesis:
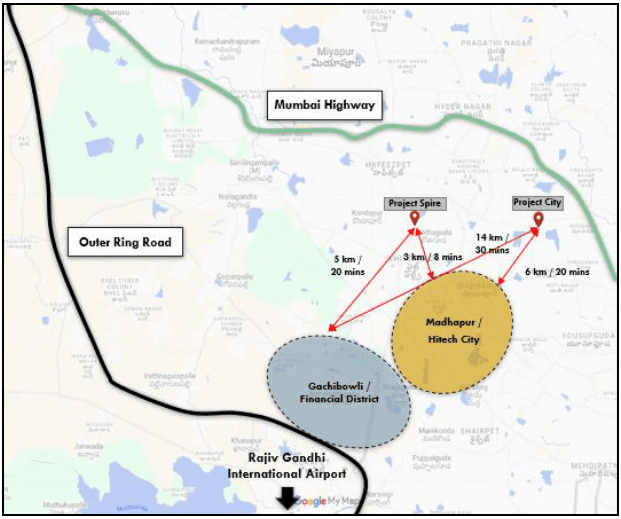
While there is a steady buildup of housing inventory over last few years, we believe an active office market (which is an engine for housing demand) reaffirms structural health of the residential market. Project which are closer to the core office markets of Hyderabad should witness decent absorption levels. Private credit can play active role to bridge cash flow gaps and sustain project execution especially for healthy developers having well-located projects with good product fitment.